Domino’s third-quarter report presents two very different versions of growth in the same set of numbers. The pizza chain added 175 net stores worldwide and increased operating income 8.3%, even though comparable sales rose only 0.3% in the United States and 0.2% internationally.
For restaurant operators, that split matters more than the headline earnings beat. It shows a franchised chain generating stronger corporate profit through a larger royalty base and more productive supply-chain operations while sales growth at established restaurants remained close to flat.
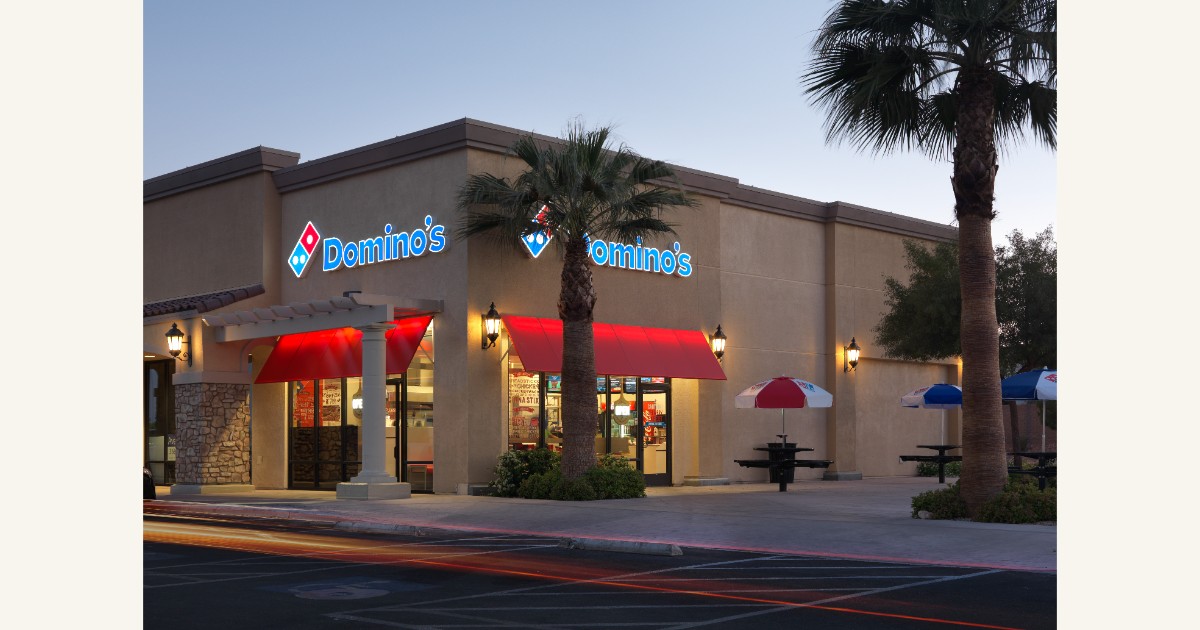
Domino’s ended the quarter on September 6 with 22,706 restaurants: 7,257 in the United States and 15,449 internationally. During the quarter, the system opened 228 restaurants and closed 53, producing net growth of 175. The U.S. accounted for 26 net additions; international markets accounted for 149. Over the trailing four quarters, net growth reached 956 stores.
That expansion helped global retail sales rise 3.2% excluding foreign-currency effects. Retail sales totaled $4.84 billion for the quarter, up from $4.70 billion a year earlier. The gain was not primarily a same-store-sales story. U.S. comparable sales slowed to 0.3% from 5.2% in the year-earlier quarter, while international comparable sales excluding currency effects slowed to 0.2% from 1.7%.
Corporate revenue still increased 3.4% to $1.19 billion. Domino’s attributed the $38.5 million increase mainly to higher supply-chain revenue and global franchise royalties. The supply-chain business benefited from higher order volume and a 2.2% increase in the food basket price charged to stores. Royalty and fee revenue benefited from net store growth over the trailing four quarters.
The supply-chain margin is an important part of the result. Gross margin in that segment improved 0.9 percentage points to 12.2%, which the company attributed primarily to procurement productivity. Supply-chain revenue was $746.2 million, roughly 63% of total corporate revenue for the quarter.
Those mechanics helped operating income reach $241.8 million, up 8.3%, and net income reach $152.2 million, up 9.2%. Diluted earnings per share increased 12.7% to $4.60; Domino’s said the increase reflected higher net income and a lower average share count after repurchases.
The quarter also shows why corporate results and restaurant-level demand cannot be treated as the same measure. Domino’s corporate revenue includes supply-chain sales, franchise royalties, fees and advertising revenue. Global retail sales measure consumer spending across company-owned and franchised restaurants and are not included wholesale in corporate revenue. Ninety-nine percent of the system was franchised at quarter-end.
Company-owned U.S. store revenue declined because Domino’s refranchised certain markets during the second quarter. That decline partially offset the higher supply-chain and royalty revenue, but it also leaves the company even more dependent on franchise economics and store-level execution.
New CEO Joe Jordan, who moved into the role October 1, said the next opportunity is to get closer to customers, improve franchisee profitability and turn the chain’s best performance into everyday execution. The third-quarter figures define the immediate challenge: the system is still opening restaurants and converting scale into corporate profit, but established-store sales are providing very little momentum.
For franchisees, the next test is whether promotions, product innovation and operations can lift order frequency without surrendering the margin improvement visible elsewhere in the system. For Domino’s corporate operation, unit growth and supply-chain productivity provided a buffer this quarter. They are useful growth engines, but they do not eliminate the need to strengthen demand at the restaurants already open.